Asset Review:  Wren Staked tGBP
| Item | Detail |
|---|---|
| Asset | Wren Staked tGBP |
| Asset type | Sterling stablecoin wrapper |
| Deployment | Ethereum (0x57C3…B7aE) |
| Review date | 2 October 2026 |
| Official links | Website · Docs · GitHub · X |
- Asset overview
- At a glance
- Backing and yield
- Exits and market liquidity
- Issuer and organization
- Governance and control
- Valuation and oracle considerations
- Security and operational history
- Risk summary
Asset overview
Wren Staked tGBP (wstGBP) is an Ethereum wrapper operated by Wren Spire, an Arb Capital company.1 It wraps tGBP, a sterling stablecoin issued by a separate company, BCP Technologies, and backed by offchain sterling reserves.23 It uses a custom ERC-20 wrapper rather than the ERC-4626 vault standard.2 Users deposit tGBP to receive wstGBP. As Wren raises the published conversion rate, each wstGBP becomes redeemable for more tGBP.2 Wren’s website attributes these increases to income from tGBP’s offchain reserves.4
Redemptions carry a 0.25% exit fee, which Wren’s administrators can change.567 Redeeming tGBP for pounds through BCP requires an eligible account.3
At a glance
- Yield: Income from tGBP’s offchain reserves
- Exposure: BCP’s reported tGBP reserves: approximately 60% money-market funds, 22% bonds and 17% cash (31 August 2026).
- Loss buffer: No junior tranche or separately funded backstop.
- Valuation: Wren’s feed quotes tGBP per wstGBP after the redemption fee.
- Redemption: Returns tGBP less a 0.25% fee, with no cooldown. Wren can change both the fee and cooldown.
- Liquidity: One 2-of-3 Safe controls liquidity in the main onchain exit pools.
- Access: Transfers are screened against tGBP’s ban list. Wren’s terms exclude US persons and UK residents, among other groups.
- Control: Wren’s 3-of-5 Safe can issue unbacked shares and burn holder balances. BCP separately controls tGBP minting and upgrades. Neither layer has an onchain execution timelock.
- Recovery: Depends on access to BCP’s reserves. It is unclear whether holders would be paid before other creditors if BCP became insolvent.
Backing and yield
Wrapper backing and tGBP reserves
The wrapper holds about 63,000 tGBP, enough to cover outstanding redemption claims after fees. It holds the tokens directly rather than deploying them into a yield strategy.25
BCP’s 31 August 2026 reserve report lists about £20 million in assets, enough to cover outstanding tGBP across eight chains. Roughly 60% was in money-market funds, 22% in bonds and 17% in cash.8 Andersen checked records supplied by BCP; this was not an audit or assurance review.8
The available disclosures do not identify the money-market funds, bond maturities or settlement arrangements, making it difficult to assess how quickly BCP could meet a large sterling redemption.8 Reserve losses or settlement delays could affect holders’ sterling proceeds even while the wrapper’s tGBP balance remains unchanged.
Yield funding and distribution
Since deployment in April 2026, the wrapper has received about 500 tGBP in top-ups outside ordinary minting.9 Redemption fees also stay in the wrapper, rather than being paid to Wren.210
Wren decides whether to reflect these top-ups and retained fees in a higher conversion rate.10 Its price module does not check that an increase is funded.11
Wren’s website attributes yield to a commercial agreement funded from tGBP’s offchain reserves.4 Its protocol terms instead describe discretionary payments from Wren or an affiliate’s corporate funds and expressly exclude BCP funding or payments of reserve income.10 The transfers show that backing was added, but not where the money ultimately came from.9 Holders have no contractual entitlement to future rewards.10
Exits and market liquidity
Native redemption
Holders redeem wstGBP against the wrapper’s tGBP balance, without relying on AMM liquidity. There is no cooldown, and the minimum redemption is 1 wstGBP.25 If the wrapper lacks enough tGBP, redemption still burns the holder’s requested wstGBP and pays what is available. The unpaid amount remains a fixed tGBP claim, with no priority over later redemptions.2
Wren’s administrators can issue wstGBP without adding tGBP, reducing the backing available per token.26
If Wren stops new redemptions, existing claims can still be collected, provided the wrapper has enough tGBP and BCP allows the transfer.212
Wren provides two ways for trading apps to mint or redeem through the wrapper: a direct adapter and a Uniswap v4 “backstop” hook. Both require immediate payment in full when redeeming; otherwise, the transaction fails and the holder keeps their wstGBP.1314 Both rely on the wrapper’s existing backing and access rules, so neither provides an independent source of liquidity.1314
Selling into onchain markets
The main onchain route redeems wstGBP for tGBP and sells it across the two principal Uniswap tGBP/USDC pools. On 1 October 2026, this route could handle about 40,900 wstGBP within a 2% downward price limit per USDC pool, at a cost of about 1.09% in fees and price impact.15
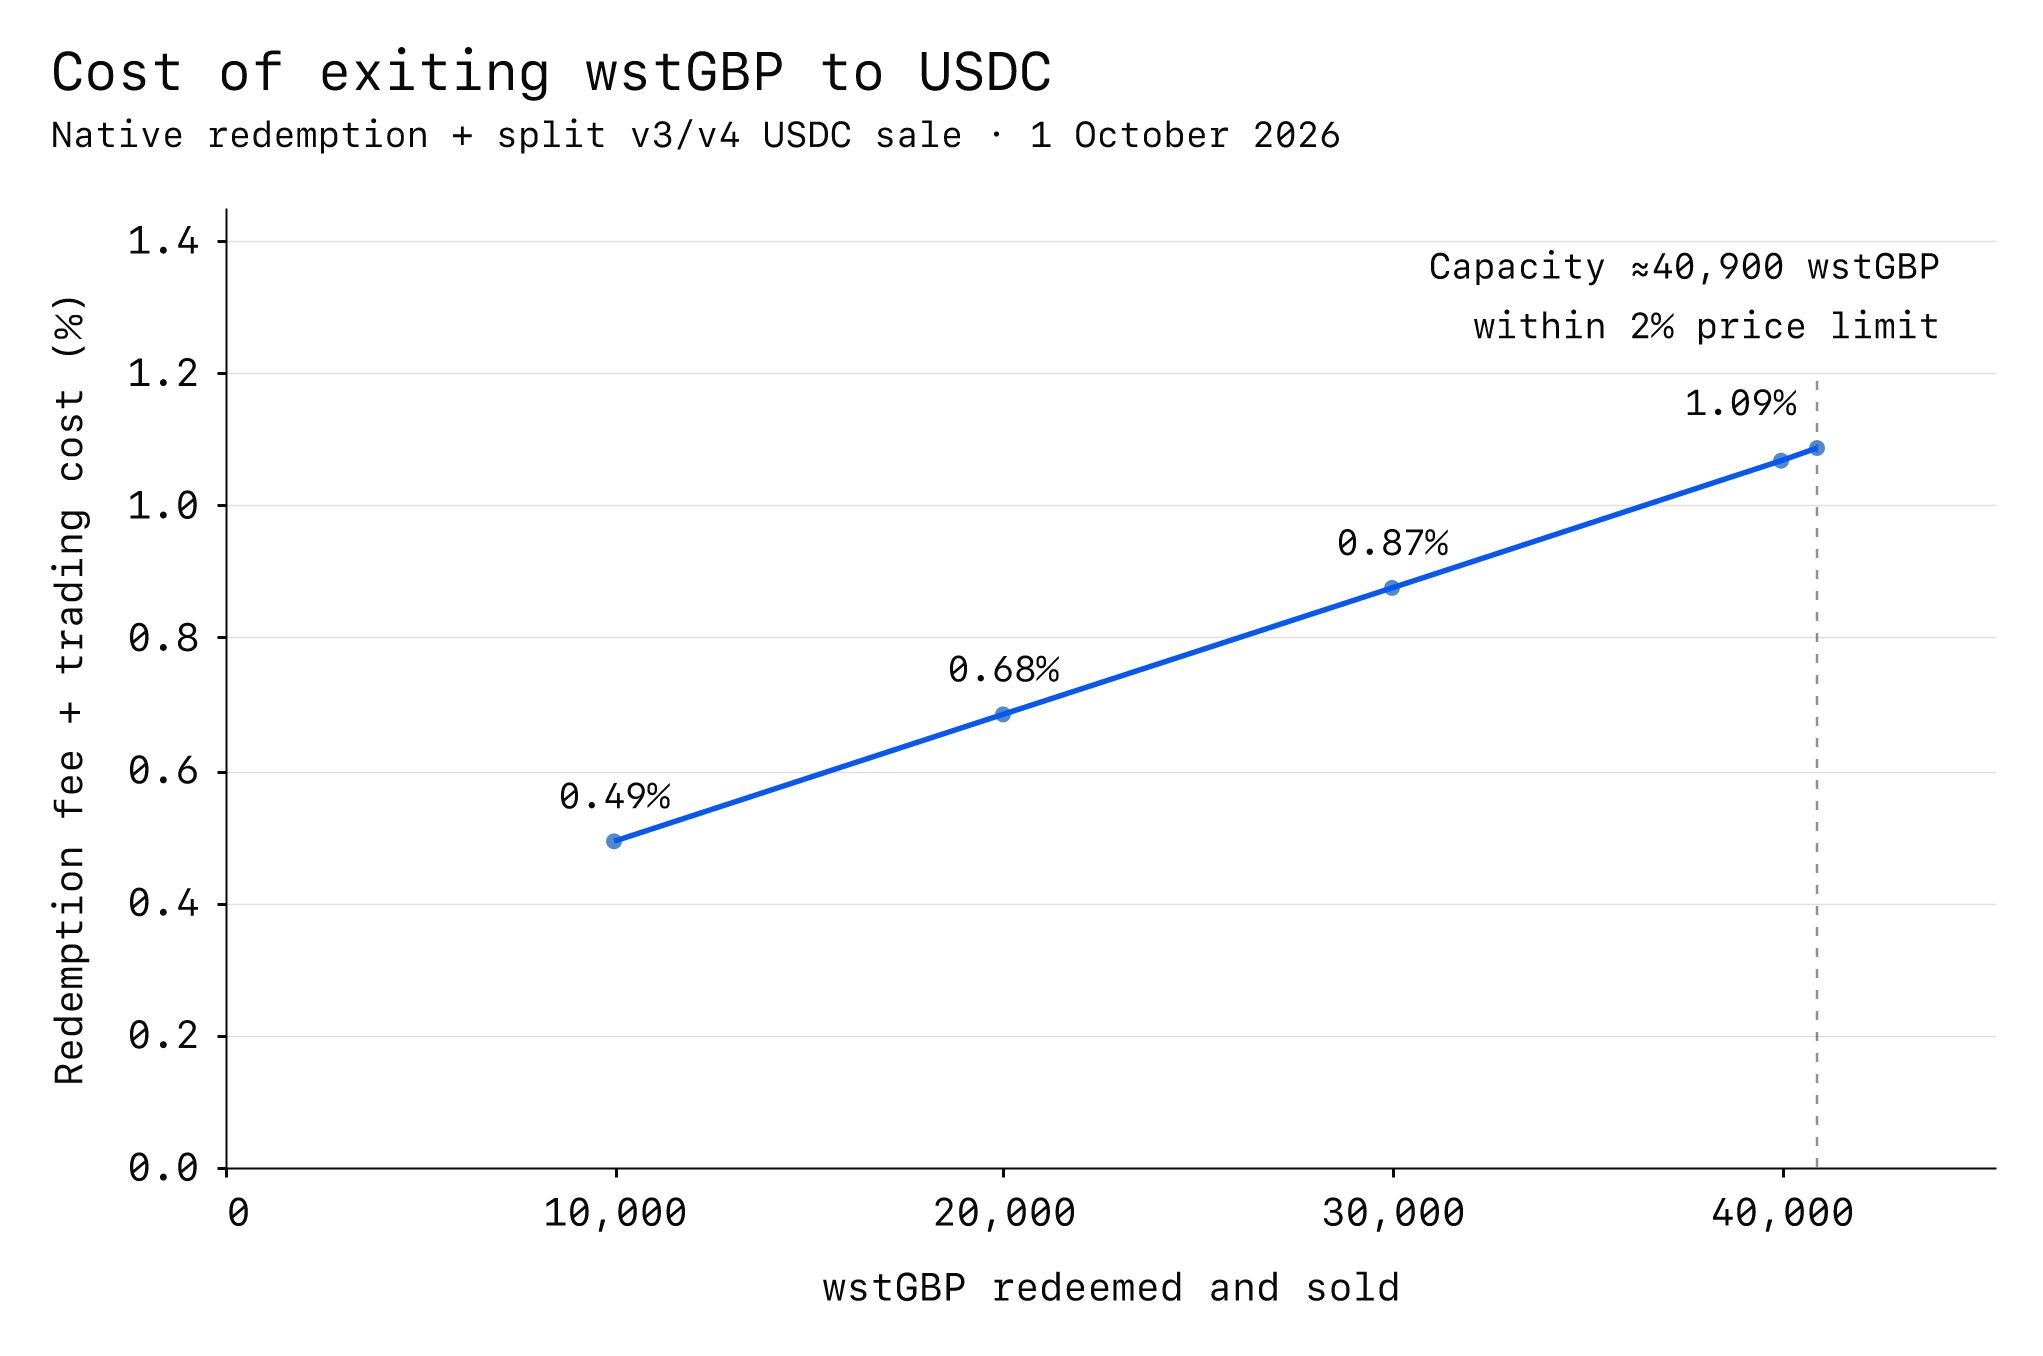
Figure 1. Cost and capacity of wstGBP exits to USDC, 1 October 2026. Source: yRisk calculations.15
Costs include redemption and swap fees, measured against gross wrapper value at the starting v3 pool price. Estimates use a 2% downward marginal-price limit per USDC pool.15
The Curve wstGBP/tGBP pool is now the main market for selling wstGBP for tGBP. On 1 October 2026, it held about 49,600 wstGBP and 29,700 tGBP.16 Selling 10,000 wstGBP through Curve and then the same USDC pools would cost about 0.52% in fees and price impact.15
Liquidity control and alternative venues
One 2-of-3 Safe holds 99.8% of the Curve pool’s LP tokens and owns the principal tGBP/USDC v3 and v4 positions. It withdrew its entire direct wstGBP/tGBP v3 position on 28–29 September 2026. All three pools therefore depend on the same liquidity provider.1617
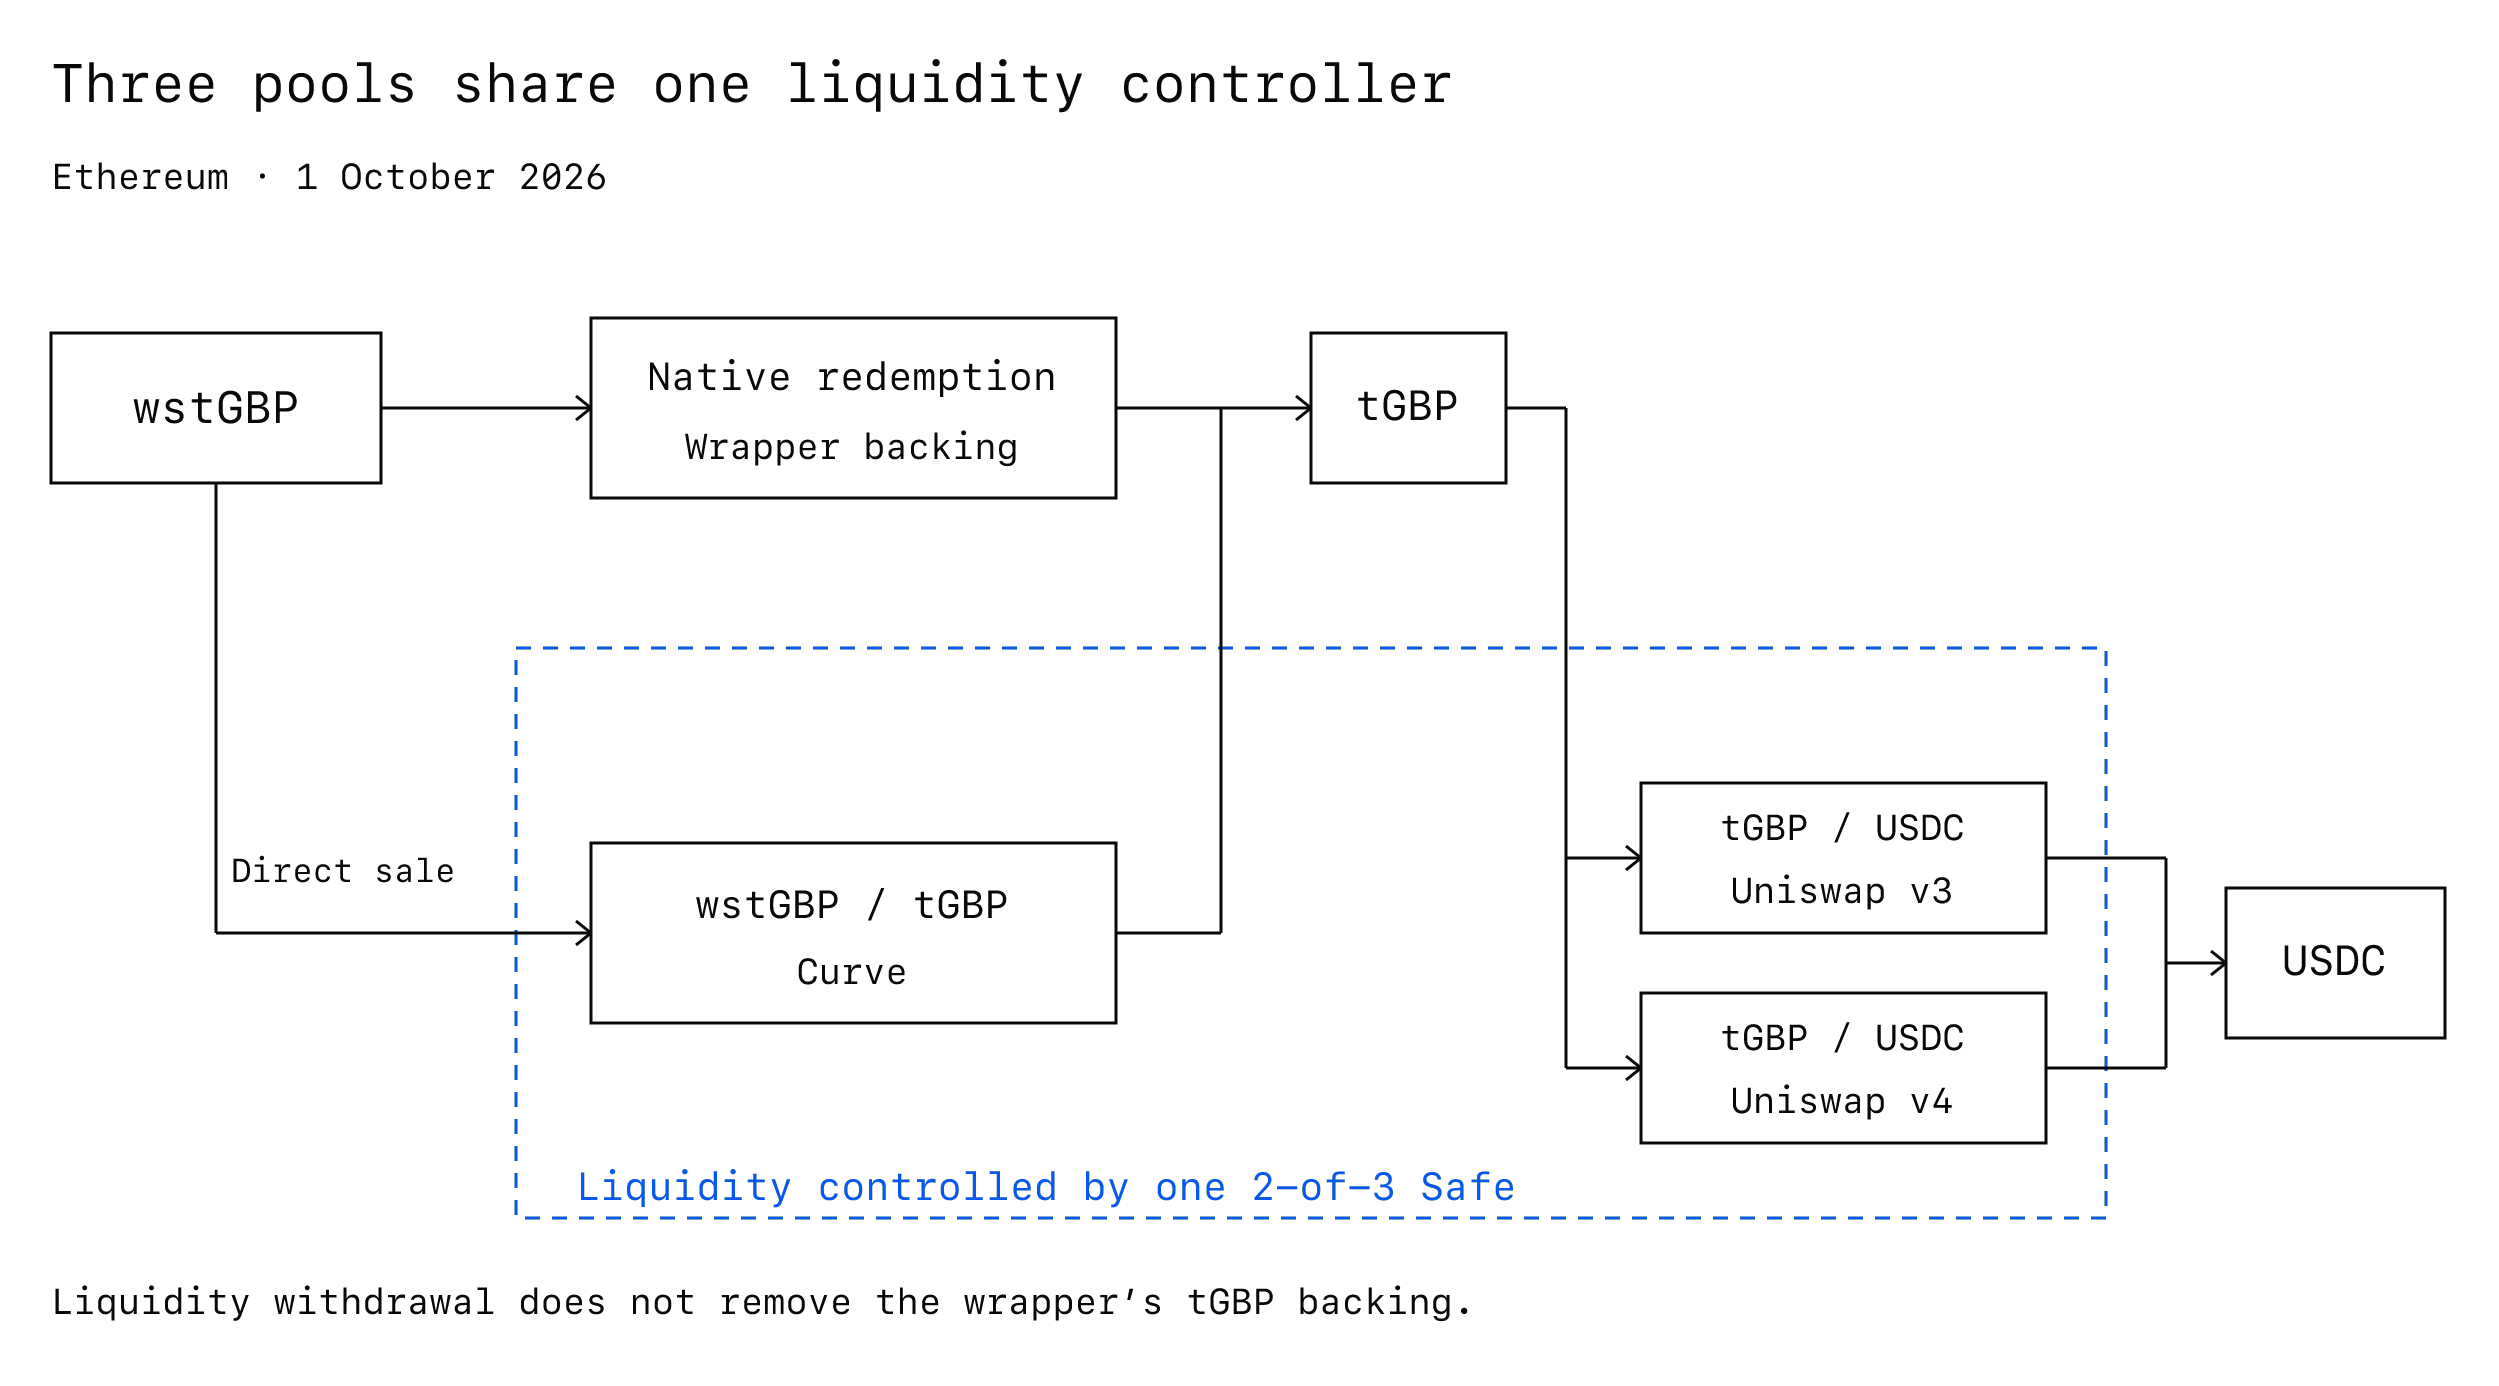
Figure 2. Exit routes and liquidity ownership, 1 October 2026. Source: yRisk analysis.1617
Without the Safe’s positions, neither main tGBP/USDC pool would have offered liquidity within 2% of its price on 24 September 2026.18 Holders could still redeem wstGBP for tGBP, but would need another venue to sell it for USDC at a comparable price.
The smaller wstGBP/WETH and wstGBP/USDC pools also share control. A 2-of-5 Safe owns liquidity positions in both and controls their dynamic swap fees, up to a 10% ceiling.17 Two of its signer addresses are also signers on Wren’s controlling Safe.17 Other providers supply liquidity too, but these pools do not offer wholly independent alternatives.
On 24 September 2026, the Curve tGBP/frxUSD pool held about 2,600 tGBP and 1,500 frxUSD, providing a much smaller alternative.19
Centralised exchanges and bank exits
Kraken’s tGBP/USD and Coinbase’s tGBP/USDC markets provide alternatives to onchain sales. Their order books showed approximately 128,000 and 158,000 tGBP of bids respectively within 0.10% of the best bid, before fees.20 Using those bids requires an eligible exchange account and supported deposits, and orders may disappear while tokens are being transferred.
Receiving sterling directly from BCP requires an eligible, verified account.3 Arb Capital reports payment on the next business day, but BCP’s public terms do not guarantee that timing.321 Standard minimums and total fees remain unclear.322
Issuer and organization
Wren’s role and the holder’s rights
Wren Spire (BVI) Ltd issues wstGBP and operates its website. Arb Capital provides development and technical administration, according to its intake response.21 Wren presents itself as an Arb Capital company, whose CEO Jawaad Bokhari and CTO Brian McMichael have backgrounds in trading and MakerDAO respectively.1
Wren’s terms do not promise repayment, returns or coverage of shortfalls from its own funds or insurance.10
US persons and UK residents are excluded from participation under those terms, among other groups, even where onchain transfers remain possible.10 Disputes are subject to BVI law and arbitration. The terms generally cap Wren’s liability at US$100, with exceptions including fraud, wilful misconduct and liabilities that cannot legally be excluded.10
BCP and sterling redemption
BCP Technologies Ltd issues tGBP. Companies House identifies Benoit Marzouk as its majority shareholder.23 Its unaudited accounts for 31 March 2025 report about £200,000 of net assets.23 These accounts predate the current product scale and do not establish funds available to support tGBP holders.
BCP’s terms promise one pound of sterling reserves per tGBP, held separately from corporate funds for users’ exclusive benefit.3 The redemption right passes to subsequent holders, but exercising it requires an approved BCP account. BCP can refuse registration, impose redemption limits or suspend services for compliance reasons. Its terms also allow forfeiture for certain breaches.3 We could not establish which account agreement applies to tGBP redemption.24
DIA names Banking Circle, Clear Junction and Swissquote as cash counterparties, and Interactive Brokers for short-term gilts.25 Naming these firms does not show how the reserves are held, what terms govern the accounts or whether holders would be paid before other creditors in an insolvency.825
The FCA identifies BCP as a registered cryptoasset firm in its sandbox records.26 BCP states that tGBP is not electronic money and has no Financial Services Compensation Scheme protection.22
Governance and control
Administrative powers
The core wstGBP contract cannot be upgraded.2 Wren’s 3-of-5 Safe can upgrade its operating modules, change the conversion rate, fees and cooldowns, and stop minting or redemption without an execution delay.6 Arb Capital says two of the five signers work for separate external security firms.21 Their identities were not supplied, and the threshold can still be met by the other three signers.
The same Safe can issue wstGBP without depositing tGBP and burn holders’ wstGBP without their approval or payment.26 Ordinary minting limits and market gates do not restrict this issuance.2
Administrators can bypass the fee and cooldown limits. A 100% redemption fee would burn the holder’s wstGBP without payment.7 Wren can also lower the conversion rate or raise it without a limit on the size of the change or a check on backing.11
BCP’s single administrator account controls tGBP minting, pauses, bans, contract upgrades and bridge settings, without an onchain multisignature or execution delay.6 Minting has no onchain reserve check or supply cap.12 Utila’s case study suggests this account uses MPC signing.27
Token restrictions and cross-chain exposure
wstGBP transfers and approvals are subject to tGBP’s ban list, which is currently empty.2612 A tGBP pause works differently: wstGBP can remain transferable while minting and redemption payments are blocked.28
tGBP uses LayerZero for cross-chain transfers, with messages from trusted contracts on other chains able to trigger minting on Ethereum.12 Messages arriving on Ethereum require approval from all three verifier networks—LayerZero Labs, Nethermind and Google.29
Valuation and oracle considerations
The deployed Wren aggregator reports how much tGBP each wstGBP can redeem for after fees. It reads Wren’s published rate rather than measuring backing or market prices. Its interface is Chainlink-compatible, but the rate does not come from an independent Chainlink price network.30 Arb Capital says the production rate is updated weekly: Wren determines the rate, and Arb Capital administers the onchain update.21
The feed can continue quoting a positive redemption rate while tGBP transfers or Wren redemptions are paused.28 It also does not independently reflect a tGBP depeg or reserve loss.30 Using the feed to value collateral requires a separate assessment of tGBP’s recoverable value. Treating each tGBP as £1 assumes BCP can honour its redemption promise, while valuation in another currency also requires an exchange rate.3
The feed returns Wren’s current net redemption rate, but its timestamp updates only when a changed rate is saved. It can stay old while the rate is unchanged or lag behind a new rate until that change is saved. Lending-market freshness checks must account for both cases to avoid rejecting a current quote during borrowing or liquidation.30
On 24 September 2026, the wstGBP/tGBP and tGBP/USDC Uniswap v3 pools each stored only one price observation, offering little history for a time-weighted average price (TWAP).31
Security and operational history
Operating history
All 81 recorded native redemptions since deployment in April 2026 were paid in full in the same transaction, totaling about 30,000 tGBP. The largest payment was about 10,000 tGBP.32 Checks after published rate changes also found enough backing to cover redemption claims after fees at every sampled point.32
Wren publishes an operational contact and an oracle runbook covering missed checkpoints, pauses and changed fees.1033 We found no public bug bounty programme or guaranteed recovery time.
Audit history
| Date | Audit |
|---|---|
| 16 May 2024 | OpenZeppelin: original tGBP |
| 14 April 2025 | Prototech: Maseer baseline |
| 30 October 2025 | OpenZeppelin: tGBPv2 |
| 21 April 2026 | Prototech: wstGBP Audit02 |
The first two audits cover predecessor code. OpenZeppelin reviewed the current tGBP contracts, while Prototech’s Audit02 covers Wren’s core contracts and modules.3435
The deployed source files for Wren’s core contracts and tGBP’s custom contracts match the revisions reviewed by their auditors.3435 We compared source code but did not independently reproduce the deployed bytecode.
Prototech’s current report acknowledges Wren’s ability to bypass configuration limits, as described under Administrative powers.35 OpenZeppelin identified a critical flaw that let banned senders bypass restrictions through cross-chain transfers; this was fixed in the matching tGBP revision.34
We could not confirm independent audit coverage for the deployed trading contracts, direct adapter or price feed.3335
Risk summary
Holding enough tGBP to cover redemptions does not ensure that wstGBP holders can recover equivalent value in sterling or other assets.
- Administrators can create unbacked tokens and remove holder balances. Wren’s 3-of-5 Safe reduces single-key exposure, but can issue unbacked wstGBP and burn holders’ balances without their approval or payment. BCP separately controls tGBP minting and upgrades. Neither layer has an onchain execution timelock.
- Sterling recovery depends on BCP. The issuer promises segregated reserves, but direct redemption requires an approved account. The available documents leave open how holders would access those reserves in an insolvency and how quickly a large redemption could be paid. The reserve report records sufficient assets but does not provide audit assurance.
- Onchain USDC exits depend on concentrated liquidity. One Safe can withdraw liquidity from both main USDC pools. Native redemption would still return tGBP, but selling it for USDC near current prices would require another venue.
- The quoted rate can overstate recoverable value. Wren’s feed reports the published conversion rate without checking redemption access, backing or tGBP’s market value. A lending market using it without accounting for those risks could overvalue the collateral.
- Future rewards are discretionary. Top-ups have added backing, but holders have no contractual right to continued funding or increases in the conversion rate.
Sources
-
Arb Capital, Company and team overview; Wren, Website. ↩ ↩2
-
Wren, wstGBP contract source (MaseerOne and MaseerToken) (Etherscan); Wren documentation, Architecture. ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7 ↩8 ↩9 ↩10 ↩11 ↩12 ↩13
-
BCP Technologies, tGBP terms, version 2.1, effective 6 January 2026. Sections 1–5, 8, 11 and 17–18. ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7 ↩8
-
yRisk calculations from onchain balances, supply, rates, fees and pending claims for wstGBP and tGBP (Etherscan). ↩ ↩2 ↩3
-
yRisk analysis of onchain roles and control settings for the Wren Safe, wrapper modules, tGBP ProxyAdmin and token owner (Etherscan). ↩ ↩2 ↩3 ↩4 ↩5 ↩6
-
Wren, MaseerGate implementation contract (Etherscan). ↩ ↩2
-
Andersen LLP, Independent Accountants Report, 31 August 2026, published by BCP, p. 2. Coverage, reserve shares and loss cushion are yRisk calculations. ↩ ↩2 ↩3 ↩4
-
yRisk analysis of tGBP transfers into the wrapper (Etherscan). ↩ ↩2
-
Wren Spire, Protocol terms, version 1.0, effective 9 July 2026; updated 10 July 2026. Sections 2–7, 11, 14 and 18–19. ↩ ↩2 ↩3 ↩4 ↩5 ↩6 ↩7 ↩8
-
Wren, MaseerPrice implementation contract and Price module (Etherscan). ↩ ↩2
-
BCP Technologies, StableTokenV1OFT implementation contract and tGBP proxy (Etherscan). ↩ ↩2 ↩3 ↩4
-
Wren, WsgemDirectAdapter contract (Etherscan); Wren documentation, Uniswap v4 integration guide. ↩ ↩2
-
Wren, WsgemHook contract; Uniswap, Uniswap v4 PoolManager contract (Etherscan). Wren documentation, Backstop pool guide. ↩ ↩2
-
yRisk Ethereum-fork simulations at block 26,101,791, 2 October 2026 at 02:56:23 UTC (1 October 2026 EDT): atomic native redemption or Curve wstGBP/tGBP sale, followed by split sales across the principal tGBP/USDC v3 and v4 pools. Each USDC pool uses a 2% downward marginal-price limit. Existing tokens fund the tests; the larger native exits source them through an authorized Curve LP withdrawal without changing wrapper backing or either USDC pool. ↩ ↩2 ↩3 ↩4
-
yRisk Ethereum observations at block 26,101,791, 2 October 2026 at 02:56:23 UTC (1 October 2026 EDT), for the Curve wstGBP/tGBP pool, LP ownership and the existing Uniswap positions. Curve deposit, 28 September 2026; final v3 withdrawal, 29 September 2026. ↩ ↩2 ↩3
-
yRisk analysis of position ownership and Safe settings, using the v3 position manager, v4 position manager, USDC hook and WETH hook contracts (Etherscan). ↩ ↩2 ↩3 ↩4
-
yRisk fork simulations after the main LP Safe withdrew its positions. Neither principal USDC pool consumed any tGBP within the tested price range. Wrapper backing remained unchanged. ↩
-
yRisk onchain reads of the tGBP/frxUSD Curve pool (Etherscan): balances, LP supply and the main Safe’s direct LP holding. ↩
-
yRisk calculations from Kraken’s tGBP/USD order book and Coinbase’s tGBP/USDC order book, collected later on 24 September 2026 than the onchain observations. ↩
-
Brian McMichael, CTO of Arb Capital and Technical Administrator for Wren Spire BVI, completed yRisk asset-review intake, received 29 September 2026. ↩ ↩2 ↩3 ↩4
-
Companies House, BCP Technologies: Company record, Persons with significant control and Accounts for 31 March 2025. ↩ ↩2
-
BCP Markets, General terms of service. ↩
-
DIA, Proof of Reserves for tGBP, 19 May 2026. ↩ ↩2
-
Financial Conduct Authority, Regulatory sandbox accepted firms, BCP Technologies entry, 2021–2025 group. ↩
-
Utila, BCP Technologies case study. ↩
-
yRisk Ethereum-fork simulations using existing holder balances and independent starting states. Administrative stress scenarios are hypothetical. ↩ ↩2
-
yRisk analysis of Ethereum bridge settings, using the LayerZero endpoint and Receive library contracts (Etherscan). Verifier names follow LayerZero’s Deployment metadata. ↩
-
Wren, Aggregator contract (Etherscan); Wren documentation, Oracles. ↩ ↩2 ↩3
-
yRisk analysis of holder balances, pool events and position NFT ownership (Etherscan). Dexscreener’s wstGBP pairs used for venue discovery. ↩
-
yRisk reconstruction of Wrapper transactions (Etherscan) from deployment through 24 September 2026, with historical backing checks after published rate changes. ↩ ↩2
-
Arb Capital, Internal hook review, 9 June 2026, Periphery audit scope and Aggregator operations guide. ↩ ↩2
-
OpenZeppelin, tGBP audit, published 30 October 2025; work performed 11–13 August 2025. Source comparison: fix revision 99b3618. ↩ ↩2 ↩3
-
Prototech Labs, wstGBP Audit02, 21 April 2026. Source comparison: revision b73c7073. ↩ ↩2 ↩3 ↩4